
The months stopped being random once the books were right
A fiber splicing subcontractor had skilled crews and carrier clients, and a bank account that never settled into a rhythm.
What it looked like from the owner's chair
Some months looked great. Some were a disaster. No rhythm to it, and no way to predict which kind of month was coming. His wife was handling the books after hours, and that isn't carelessness, subcontractor accounting is genuinely hard and it comes with no manual. Costs weren't going to the right places, so the real picture was invisible.
What was actually happening
Once the books were clean, the ups and downs made sense. Time and material fiber work comes in bursts, and overhead keeps going between them. A slow month still has a full month of cost against part of the revenue. The rates were also built on busy-month assumptions. They didn't use honest utilization across a full year. One winter month shows it best: $141,000 of project costs against $144,000 of revenue. That leaves almost nothing before overhead.
This is a known failure and it has a page of its own, with what it costs and how to size it in your business.
The work
We rebuilt the books so costs go where they belong, then set the time and material rate against real utilization across the year rather than the months when everybody is busy. The monthly cadence puts the numbers in front of him on a schedule, which is what turns those ups and downs into something you can plan around.
The result
He sees his numbers every month now, knows which months are structurally profitable and which ones consume margin, and knows what his time and material rate actually has to be. He is deliberately building structured cabling work, which bills on contract and on a predictable schedule, to operate alongside the time and material side and flatten the curve. Decisions come off what the business is doing, not off what it feels like it's doing.
Ten months later, net profit is up 7 times
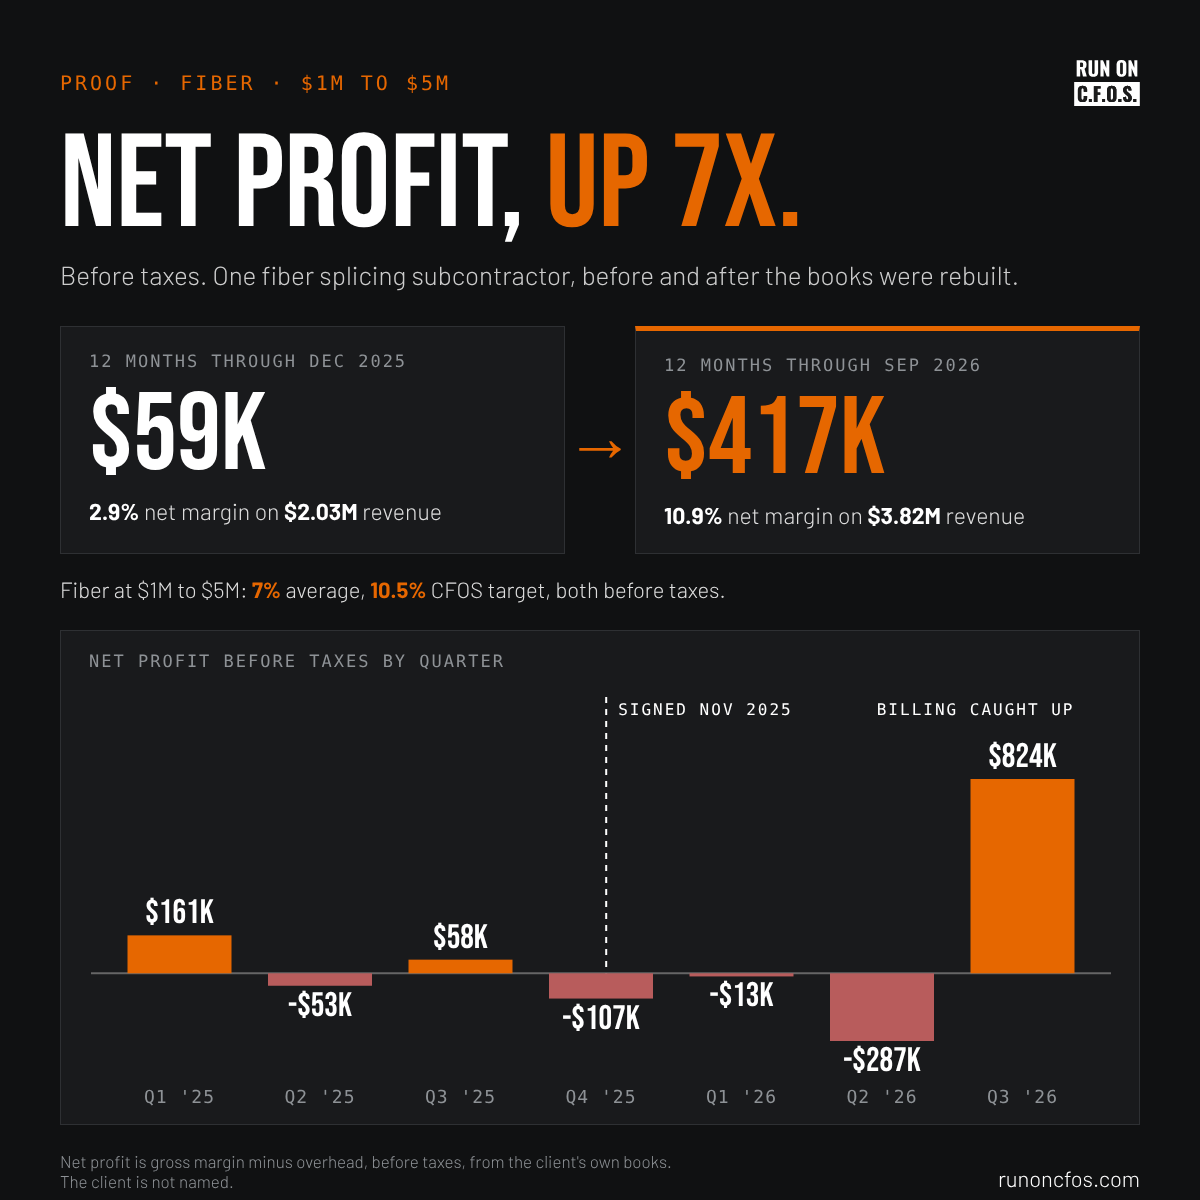
The work started in November 2025. For the twelve months through December 2025 the business brought in $2.03M of revenue and kept $59K of it as net profit before taxes, a 2.9% net margin. For the twelve months through September 2026 it brought in $3.82M and kept $417K, a 10.9% net margin before taxes.
The 2025 books showed a gross margin of about 73% and overhead of about 70% of revenue. Neither figure was real. Project cost was posting to overhead, so the jobs looked better than they were and the office looked heavier than it was. With project cost on the jobs, the last twelve months show a 44% gross margin and 33% overhead.
Not every month went up. In the first half of 2026 the business lost $300K before taxes, and most of it came in March, April and June. Part of that was billing: they were behind on sending invoices, so the cost of the work was on the books before the revenue was. The owner saw it in his monthly report by job, and he saw it that month and not at tax time. They caught up on billing in July, and July revenue alone came to $1.06M. The third quarter brought in $2.25M of revenue and $824K of net profit before taxes, and some of that's work done earlier in the year, so the twelve month figures are the fair comparison.
The balance sheet followed. From December 2025 to September 2026, equity went from $103K to $627K, working capital from $35K to $821K, and the current ratio from 1.68 to 3.61. The rise in equity matches the profit the business made in 2026 and kept.
The published fiber net profit at $1M to $5M is 7% and the CFOS target is 10.5%, both before taxes. Every net profit figure on this page is before taxes too.
Other contractors with the same problem
All 14 are on one page, filterable by which step did the work.
What owners ask about this one
What was actually wrong?
Once the books were clean, the ups and downs made sense. Time and material fiber work comes in bursts, and overhead keeps going between them. A slow month still has a full month of cost against part of the revenue. The rates were also built on busy-month assumptions. They didn't use honest utilization across a full year. One winter month shows it best: $141,000 of project costs against $144,000 of revenue. That leaves almost nothing before overhead.
What did you change?
We rebuilt the books so costs go where they belong, then set the time and material rate against real utilization across the year rather than the months when everybody is busy. The monthly cadence puts the numbers in front of him on a schedule, which is what turns those ups and downs into something you can plan around.
How long did it take?
The business didn't record a timeframe for this one, so this page doesn't claim one. What it did record is the change, which is above.
Which part of the system did it?
step 01, job cost structure, step 04, estimating system, step 05, software and bookkeeping alignment, 1 more. Installed in dependency order, which is the same order every client gets, because a step that reads from a number the one before it never established produces output that looks finished and isn't.
Do these figures apply to every fiber contractor?
No. This is one company at $1M to $5M and the numbers are its own. The cause applies to other companies. The size of the result may not. The published fiber benchmarks across all 7 revenue bands are on its trade page, and those are the figures to measure yourself against.
Wrote CONTROL, the 8 step system behind these figures. More about the author.