
Numbers you can actually underwrite against
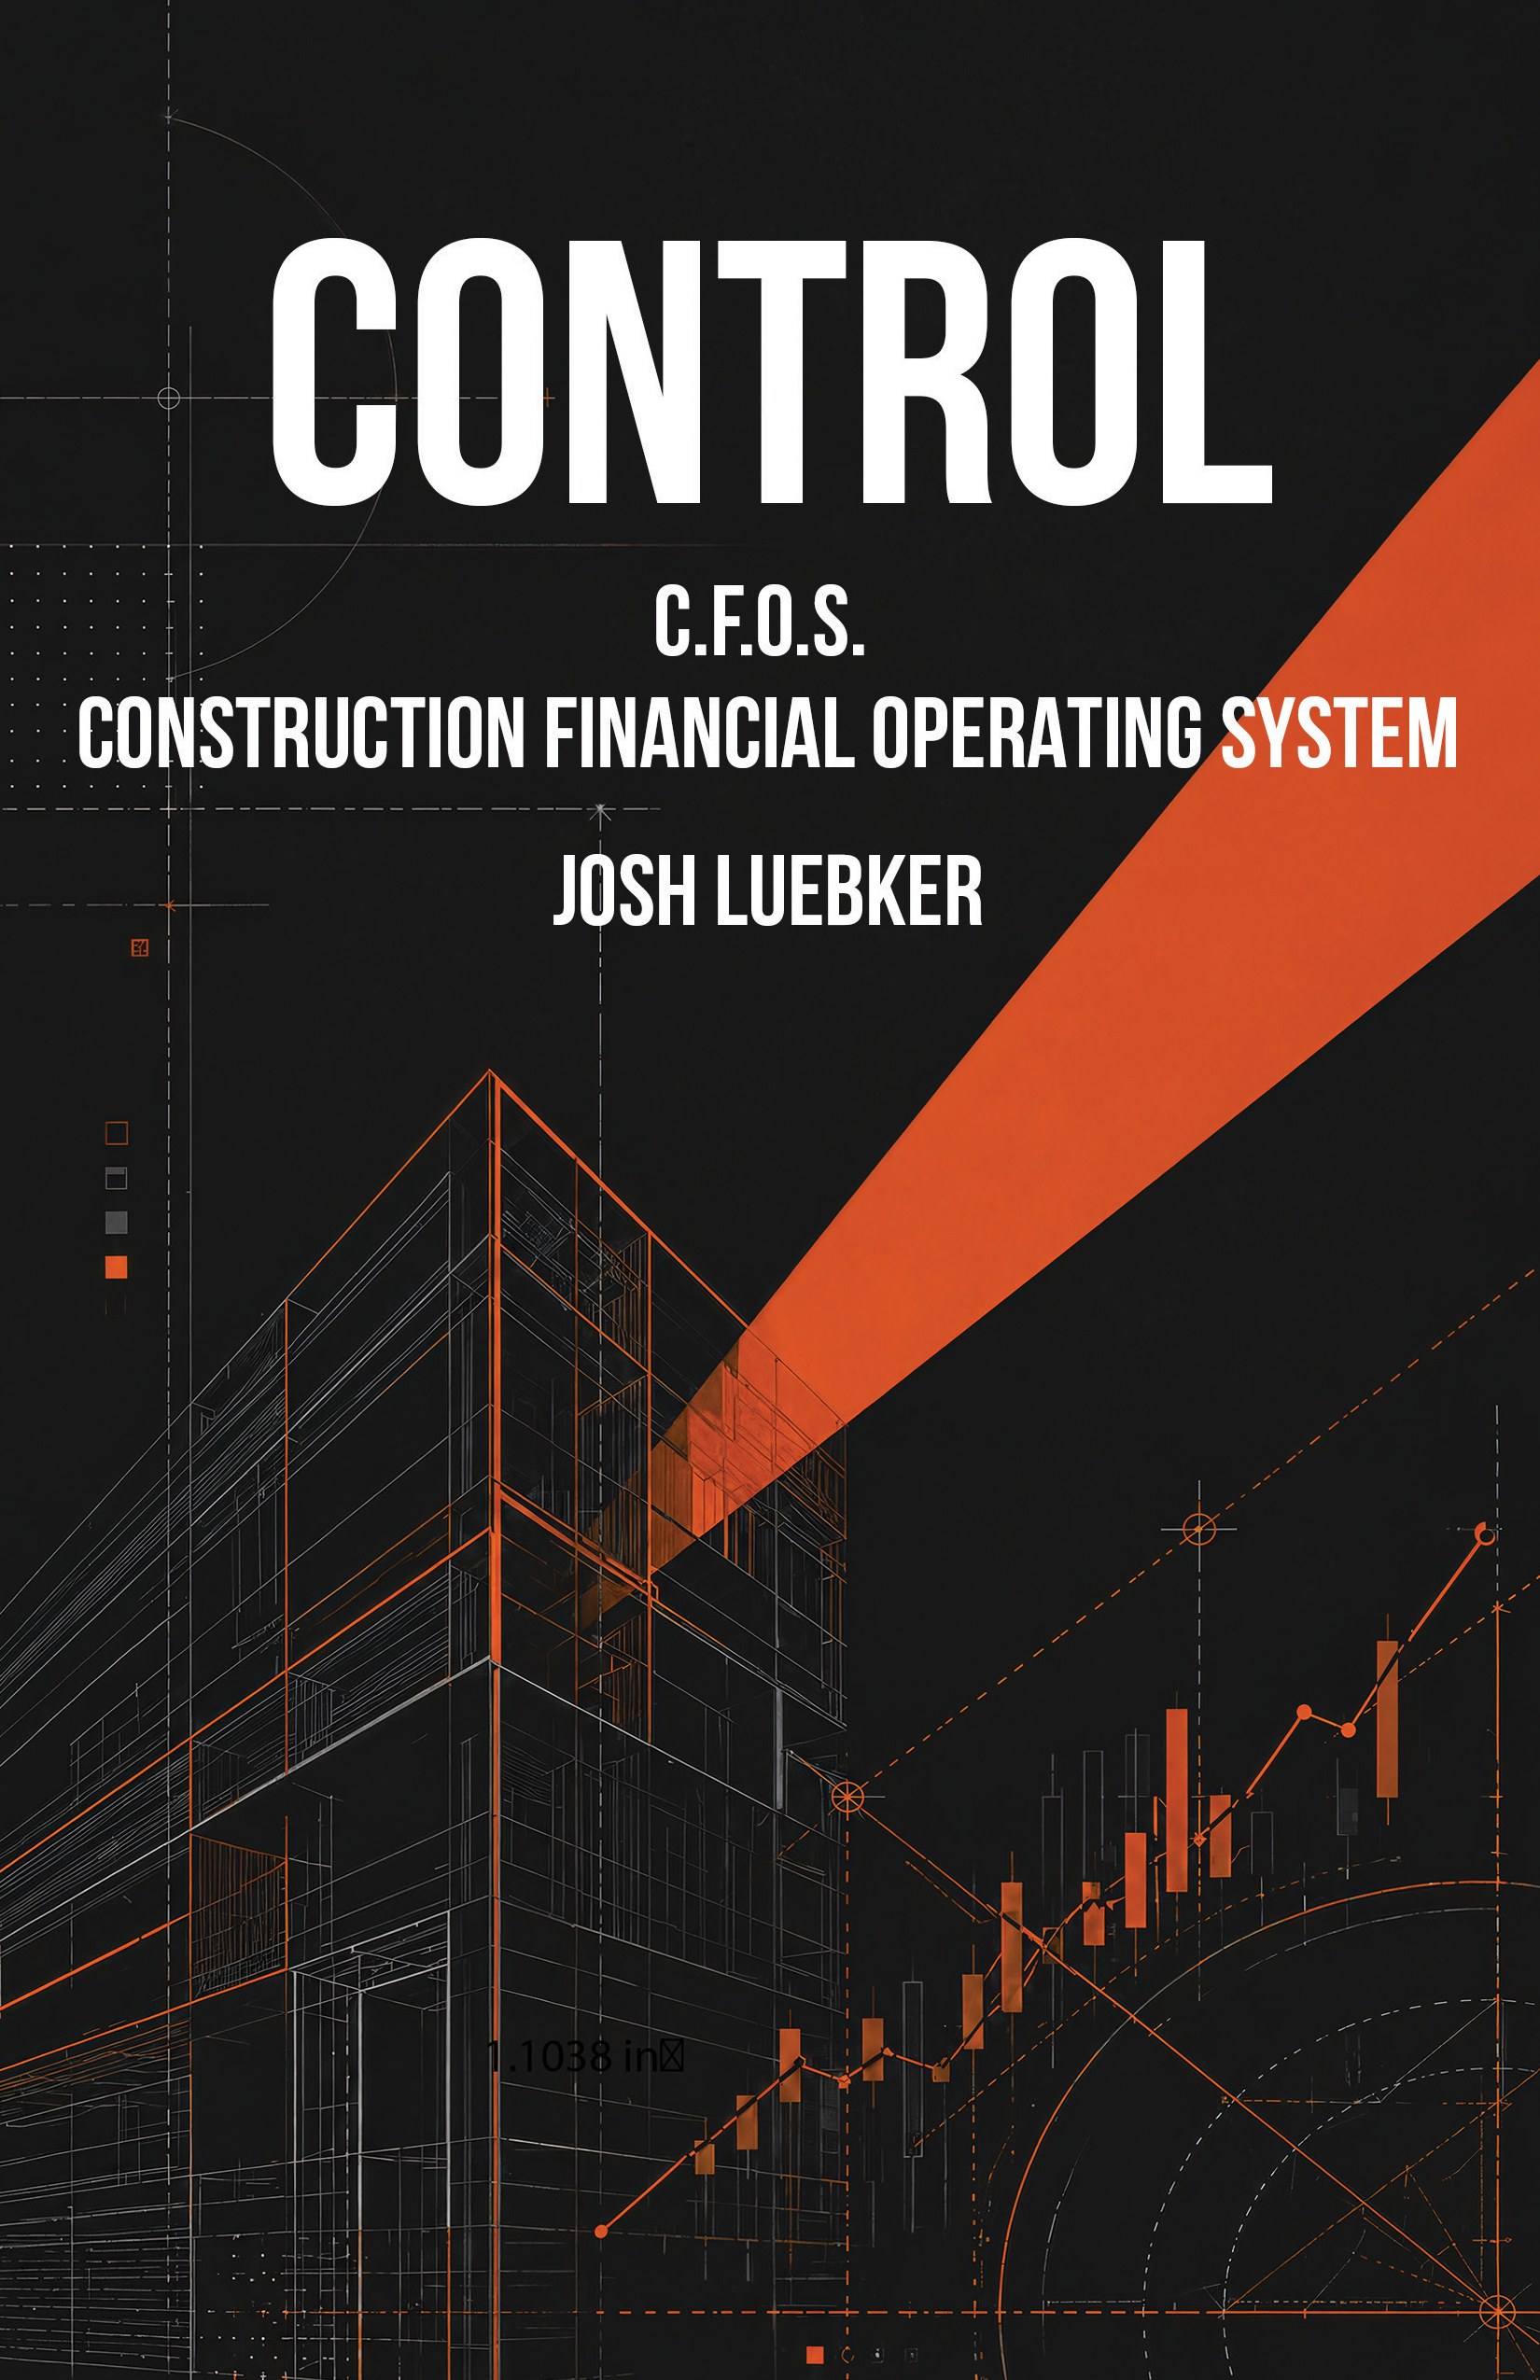
A construction borrower who can't produce a real WIP schedule on request isn't concealing something from you, he usually can't see it himself. CONTROL: C.F.O.S. Construction Financial Operating System fixes the reporting underneath the relationship, which is a better use of a year-end gift than a logoed portfolio.
The renewal that shouldn't be a surprise
Revenue looks fine. Working capital has thinned and no one flagged it. A covenant conversation starts because a number moved, and no one, the borrower included, can say why. Usually he isn't concealing anything. His company keeps its books for taxes. Those figures hold up on a return and fall apart the moment you ask about one job. When he fixes that, you see the credit more clearly.
8 steps, six templates, sixty days
What lenders ask before sending it
Why would a bank want to help a borrower fix their own reporting?
The alternative costs you more. A construction borrower who can't produce a current WIP schedule or explain a swing in working capital is a borrower whose renewal takes longer and whose covenant conversations start from suspicion. Better reporting on his end is less exposure on yours.
Is this really a gift, or does it read as the bank auditing him?
It reads as a gift if you give it as one. It's useful to him whether or not he has the loan: 8 steps and six templates that make his own business easier to manage.
What does it actually fix in his numbers?
It covers the work behind the figures you underwrite. His job costing comes from real costs. His WIP schedule is kept up every month, so no one rebuilds it at renewal. His overhead is priced at what it costs him to operate this year.
Which clients is this a good fit for?
Commercial subcontractors from $1M to $100M, doing commercial progress-payment work. If a borrower is already producing a clean monthly WIP with real job-level margins, he has the system already and won't need it.
Is it a good gift for several borrowers at once, or does that feel impersonal?
It holds up well across a portfolio because the problem it fixes is so common: most owners this size can tell you the business is busy and can't tell you which jobs are actually profitable. Saying so in a short message beats a generic thank-you-for-your-business card.
$9.99 ebook, $24.99 paperback
Get the paperback if you want him to read it. Six chapters include a QR code straight to a working file.
Buying for more than a few people? Orders of 10 or more copies cost $14.99 to $19.99 each, depending on quantity. See bulk pricing
Wrote CONTROL, the 8 step system behind these figures. More about the author.